US exports of LNG are establishing a record high this year, and the EIA expects them to set a new record high next year. It expects LNG exports to average 9.7 billion ft3/d this year (3.2 billion ft3/d more than the 2020 record high of 6.5 billion ft3/d and to exceed annual pipeline exports of natural gas for the first time. The y/y increase in LNG exports coincides with slight growth in US natural gas production. We expect US dry natural gas production to average 92.6 billion ft3/d this year, which is 1.1 billion ft3/d more than in 2020 but 0.3 billion ft3/d less than in 2019.
Because US LNG exports have grown faster than domestic natural gas production, inventories are lower than average. As of the end of September, the EIA estimates that total US natural gas inventories are 5.5% below the five-year (2016 - 2020) average. The EIA forecasts that US inventories of natural gas will begin the winter heating season on 1 November 1 3572 billion ft3/d, or 4.8% below the five-year average. Lower US inventories could contribute to more natural gas price volatility, particularly if any area in the US experiences a severe cold snap, which makes the price outlook for this winter very uncertain.
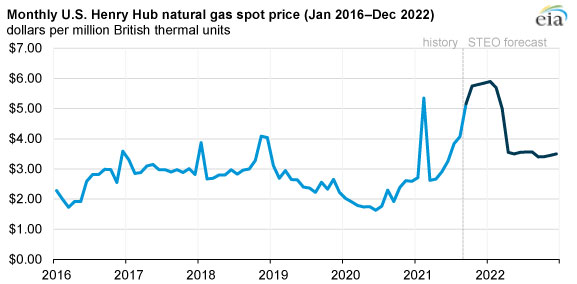
In 2Q22, the EIA forecast decreasing Henry Hub natural gas prices as anticipated growth in domestic natural gas production begins to outpace growth in US LNG exports. The EIA expects US production to average 96.4 billion ft3/d in 2022, or 3.9 billion ft3/d more than in 2021, and US LNG exports to rise by a smaller amount, 1.4 billion ft3/d, during this time period. The EIA forecasts that faster growth in production will put downward pressure on natural gas prices.